The Netherlands VAT guide
The Netherlands operates a Value Added Tax (VAT) system known locally as Belasting over de Toegevoegde Waarde (BTW). VAT is administered by the Dutch Tax and Customs Administration (Belastingdienst) and applies to most supplies of goods and services, imports and intra-EU acquisitions.
Businesses established in the Netherlands and foreign companies carrying out taxable transactions may be required to register, file VAT returns and meet additional reporting obligations such as EC Sales Lists and Intrastat declarations.
Menu
What is the standard VAT rate in The Netherlands?
21%
Standard VAT rate: 21%
The standard VAT applies to most goods and services, importation of goods and intra-Community acquisitions of goods where there are no relevant exemptions.
Reduced rates: 9%
The 9% applies to many common products or services, such as food and drink, agricultural products and services, medicines, books, daily newspapers and magazines.
0% rate
Applies to exports and intracommunity supplies.
VAT filing frequency
VAT returns are generally filed quarterly. As an exception, VAT returns can be filed on a monthly or yearly basis.
Monthly VAT returns
Monthly filing may be authorised upon request (e.g. when reclaim VAT returns are filed regularly, for example, by exporters) or required by the tax authorities in certain circumstances, including persistent late filing or payment.
Annual VAT returns
Taxable persons whose VAT amount payable does not exceed €1,883 on a yearly basis may be authorised by the VAT authorities to submit an annual VAT return.
Deadlines
Quarterly VAT returns
Most taxable persons file VAT returns quarterly. VAT returns must be filed and VAT due must generally be paid within 1 month after the end of the tax period.
Monthly VAT returns
The VAT return has to be submitted before the last working day of the month following the reporting period. The payment must be received by the VAT authorities on the same day.
Annual VAT returns
Taxable persons authorised to file annual VAT returns must generally submit the return and pay any VAT due by the end of March (the last working day of the third month following the tax year).
VAT registration in the Netherlands
Domestic businesses:
VAT registration is mandatory from your first taxable activity with no minimum threshold. You must register with the Dutch Chamber of Commerce and the Dutch Tax Administration (Belastingdienst).
Non-established businesses
Distance sales: Non-established EU businesses carrying out distance sales of goods into the Netherlands do not have to register if annual distance sales remain below €10,000 across all EU Member States. Once the €10,000 EU-wide threshold is exceeded, VAT becomes due in the country of destination. Businesses must either register locally or use the One Stop Shop (OSS) scheme.
Non-EU businesses: There is generally no threshold for non-EU businesses making taxable supplies in the Netherlands. VAT registration is required unless transaction is covered by a VAT simplification scheme, reverse charge mechanism, OSS/IOSS or marketplace deemed supplier rules.
eInvoicing requirements
- B2G mandate in place: Yes, in force since 2017.
- B2B mandate in place: Currently voluntary. The Netherlands has confirmed plans for mandatory B2B eInvoicing and digital reporting starting 1 July 2030, aligning with the EU’s VAT in the Digital Age initiative (ViDA)
- B2C mandate in place: No B2C eInvoicing mandate in the Netherlands.
- Exchange infrastructure: Peppol, Digiport
- Formats used: NL CIUS (a country specific subset f the European norm EN 16931), SI-UBL, Peppol BIS 3.0
Comply – Global VAT compliance
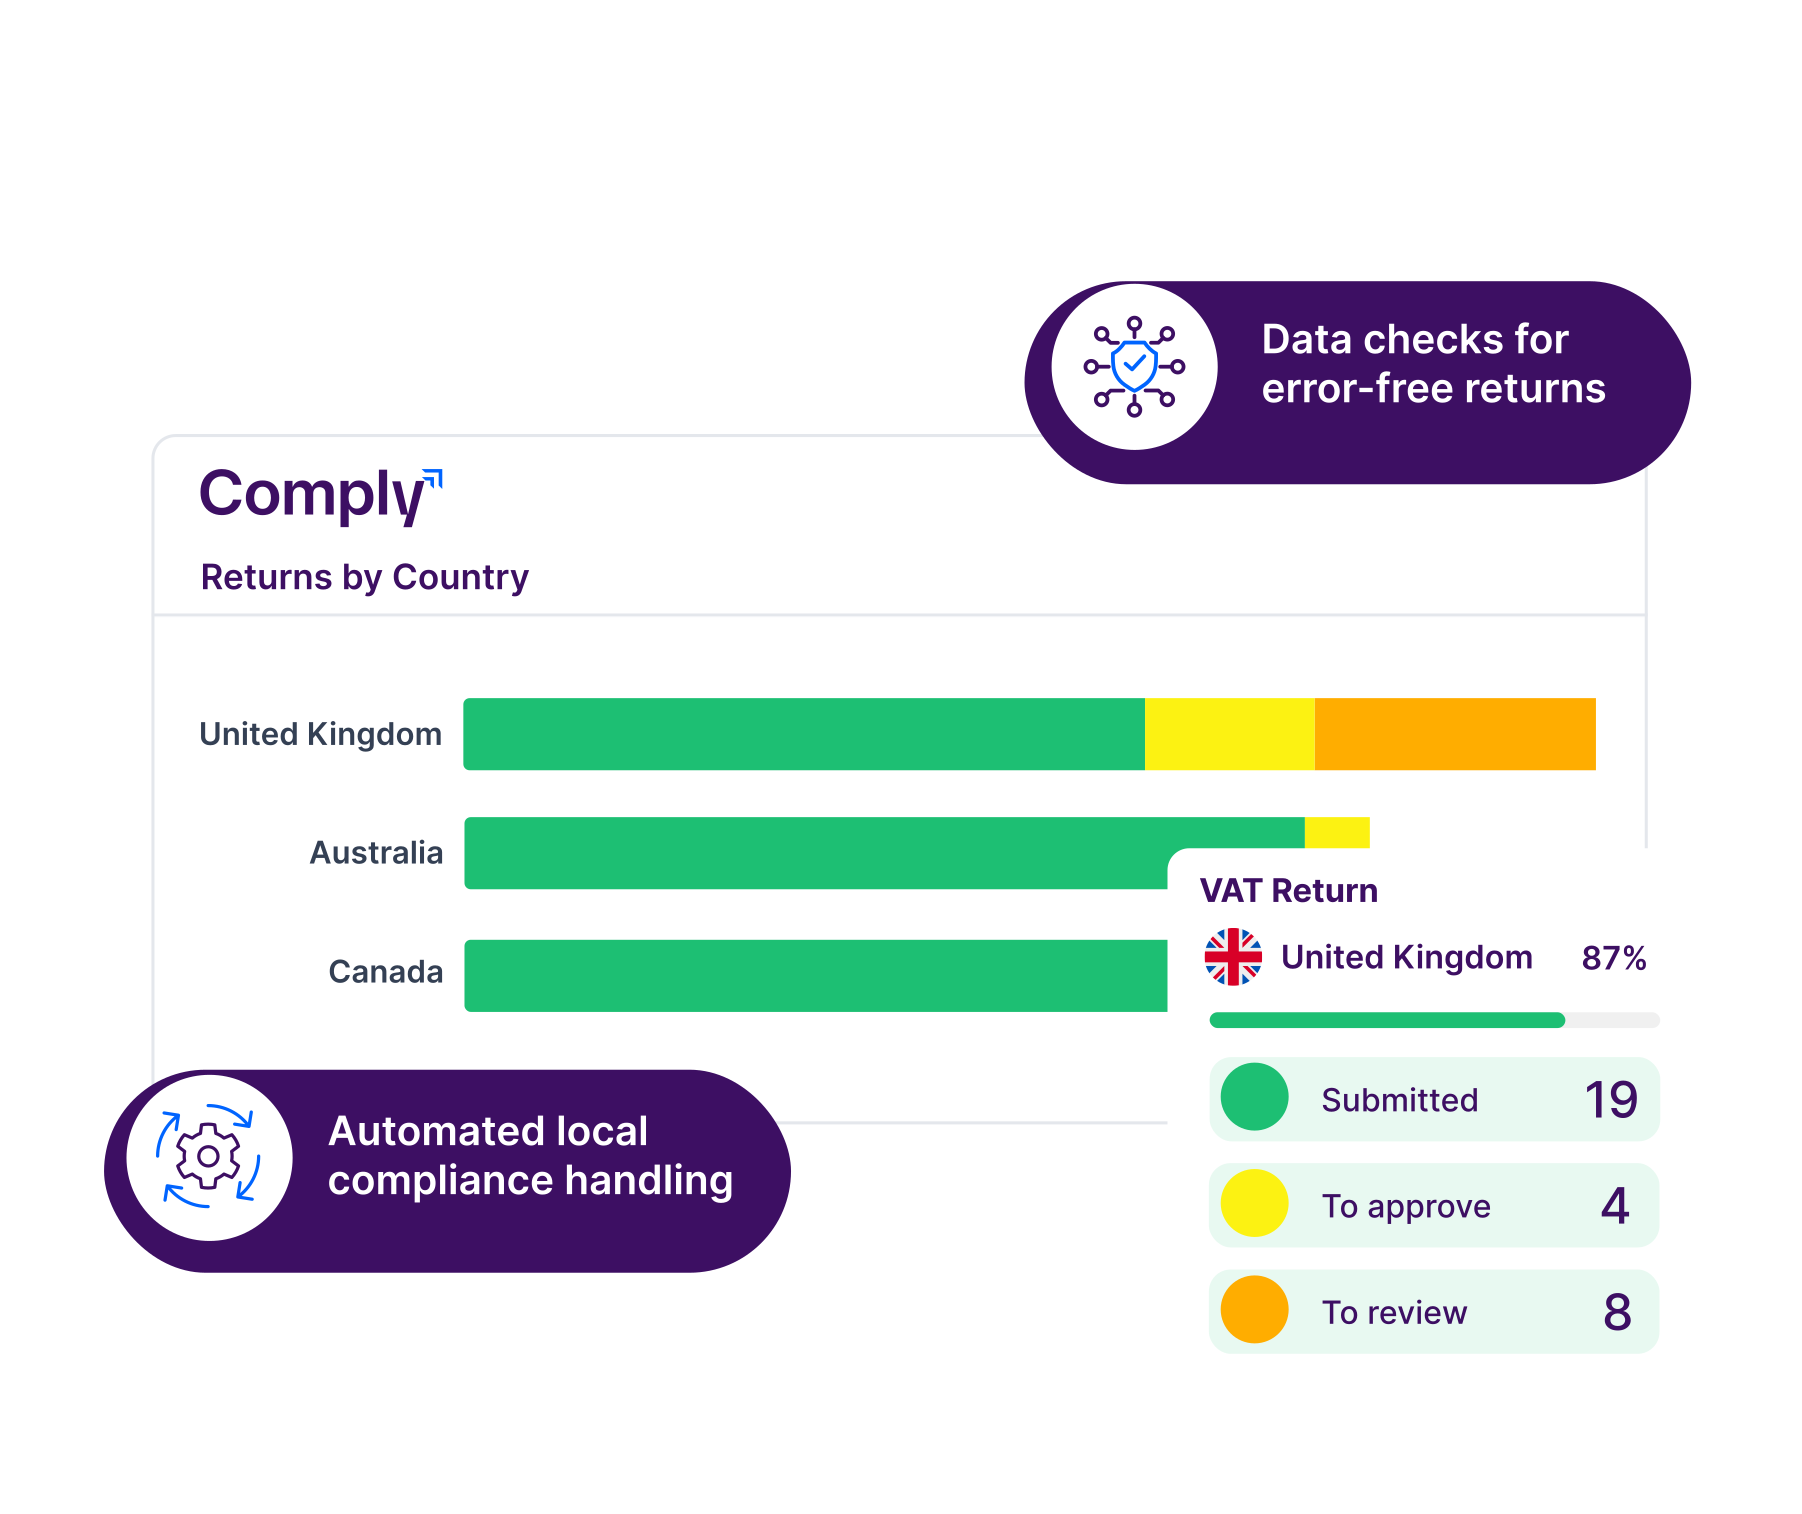
Our VAT compliance solution, Comply helps companies manage their complex, country-specific tax requirements including The Netherlands’ VAT obligations.
Using AI and machine learning, our technology puts your VAT data through over 300 automated VAT rules, checking for errors, and preparing VAT returns for approval and submission. Comply provides a full audit trail for the Dutch Tax Authorities.
Submission
To file a VAT return in the Netherlands, taxpayers must be registered with the International Office (Kantoor Buitenland) of the Dutch Tax and Customs Administration. Once registered, they will receive tax return forms periodically on which they can deduct the VAT paid.
If taxpayers supply intra Community goods and services from the Netherlands, they must submit a Statement of Intra-Community Supplies (Opgaaf intracommunautaire leveringen) at the end of every quarter via the form which can be obtained from the International Office of the Dutch Tax and Customs Administration.
Agents and fiscal representatives
Under Article 33a of the OB 1968, non-resident taxable persons must a appoint a Dutch fiscal representative in relation to their VAT obligations.
VAT penalties
For late filling: If a VAT return is submitted after the filing deadline, the Dutch Tax Administration may impose a fixed late-filing penalty of €82.
For late payment: A 7 day grace period applies if VAT is paid after the due date. If you paid your previous tax return too late or incompletely, you will receive a late payment penalty of 3% of the late payment amount, with a minimum of €50 and a maximum of €6,709.
IOSS
Since 1 July 2021, VAT exemption on low value goods has been eliminated. Currently, all sales of goods imported in the EU are generally subject to the VAT of the country of destination of goods, regardless of the value of the imported goods.
The import one stop shop (IOSS) scheme enables suppliers to collect VAT at checkout and report it through a single monthly return. To use the IOSS scheme, it is necessary to meet these conditions:
- Deliver goods from outside the EU to a customer in an EU Member State
- The sale is made to consumers (B2C)
- The intrinsic value of the consignment does not exceed €150. Shipping and insurance costs are excluded when determining the €150 threshold
- Excise goods, such as alcohol and tobacco products, are excluded from the scheme.
Intrastat
The Intrastat System was created to monitor the trade of goods between EU countries. In the Netherlands all relevant information should be passed on to Statistics Netherlands (CBS).
Registration
Businesses that are required to submit Intrastat declarations are generally notified directly by CBS based on their VAT and intra-EU trade activity.
Deadlines and Filing Frequency
Businesses must declare their intra-Community exchanges on monthly basis. The legal deadline for the submission of each monthly Intrastat declaration is the 10th working day after the end of the respective month.
Submission
Intrastat data can be submitted electronically to Statistics Netherlands via the International Trade in Goods (IDEP) platform.
.
.+02
Rise Above the Rest
Maximise your potential with our full suite
VAT compliance solution
Rise above complex indirect tax challenges with Comply, Fintua’s revolutionary platform for global indirect tax compliance.
VAT recovery solution
Recover automates the process of identifying and reclaiming VAT on business expenses, both domestically and internationally, helping you boost your bottom line.
Integrated payments solution
Pay simplifies international payments, reducing complexity and costs while ensuring compliance with local regulations and improving financial visibility.
eInvoicing solution
eInvoice enhances efficiency by digitising your einvoicing process, ensuring compliance across multiple jurisdictions and improving cash flow management.